
The First Thing to Watch in Korea Tomorrow Is Micron
Today's mood
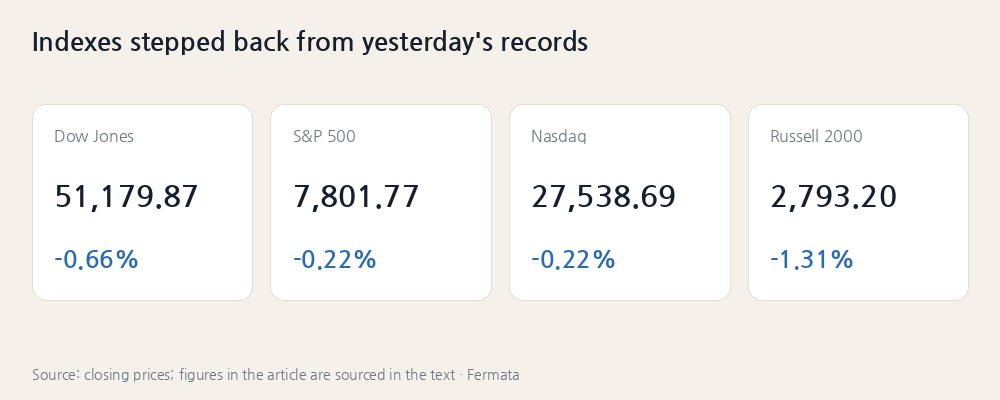
Treasury yields were the real story today, briefly touching levels last seen in 2002 before easing back. The Dow and Nasdaq, which had closed at records together the day before, both stepped back, and the Russell 2000 fell more than 1%, the worst showing among the major gauges.
Underneath the surface, moves diverged sharply by stock. Micron rallied alone on a memory-supply story, while Coinbase slid with bitcoin. This wasn’t a day when every index moved the same way — it was a day when a single variable, rates, played out differently stock by stock.
What we were watching, and what happened
Monday’s post said we’d check three things by the next session: whether Intel kept sliding on the Terafab/TSMC story, whether the 10-year yield broke above Wednesday’s intraday high (5.344%) from 5.31%, and whether SpaceX’s rally continued. There was no post for October 6, so we pick up the thread today.
Intel rose 0.55% to $113.12 today — the Terafab reaction looks like it was a one-day move. The 10-year yield touched 5.365% intraday, clearing that prior high, but eased back after a solid $39 billion 10-year note auction to close at 5.28%, barely changed from the prior session. SpaceX, meanwhile, fell 2.51%, giving back some of this week’s gains.
Treasury yields hit a 2002-era high, then pulled back
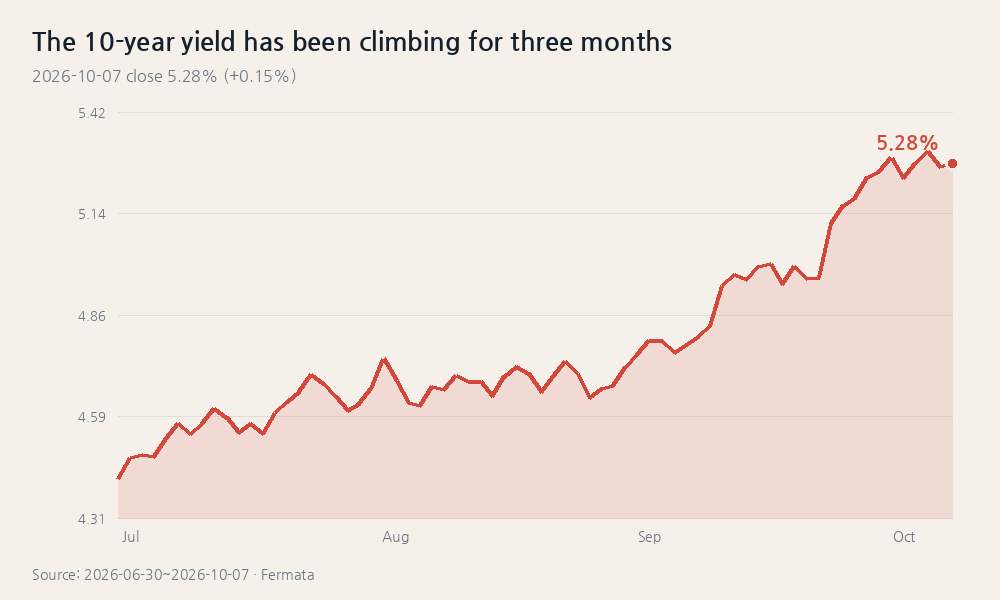
Today’s bigger story wasn’t the indexes — it was Treasury yields. The 10-year touched 5.365% intraday, its highest since April 2002, and the 30-year hit 5.732%, its highest since May 2002 (CNBC, Yahoo Finance). Both had been climbing steadily all year, but neither had gone this far.
For beginners: the 10-year Treasury yield is what the U.S. government pays to borrow money for a decade. When it rises, the present value of a company’s future earnings falls — which hits growth and small-cap stocks hardest, since more of their value sits further out. That’s part of why the Russell 2000 fell more than the large-cap indexes today.
The move didn’t hold, though. The Treasury sold $39 billion of 10-year notes to solid demand, and yields eased off their highs into the close: the 10-year ended at 5.28%, the 30-year at 5.66%. Against yesterday’s 5.27% close on the 10-year, that’s essentially flat.
Today's biggest mover was Moderna
The single biggest move among the stocks we follow today was Moderna, up 4.81% to $196.48.
Moderna joins the Nasdaq-100 before the open on October 9, taking the seat Warner Bros. Discovery is vacating. Index funds that track the Nasdaq-100 have to hold what’s in it, so buying often starts well before the effective date. That’s why Moderna ran up to $203.21 on Monday, gave it back to $187.46 on Tuesday, and bounced again today — three sessions trading on the same story.
Citi, though, cut Moderna to Sell from Neutral on September 30 — while raising its price target to $80 from $60. The point: index inclusion can lift a stock’s price, but it doesn’t change earnings or the drug pipeline.


Micron rallied again on a memory-supply story
Micron rose 4.06% to $1,088.00 today. D.A. Davidson raised its price target to $3,000 from $2,100, arguing that AI models are using more memory, and that demand will outstrip supply in 2027 and 2028 (CNBC). The firm kept its Buy rating.
SanDisk rose 1.92% the same day — it’s another memory maker. The read: when memory supply gets tight, memory makers hold up better than the rest of the chip sector.
On valuation, Micron still looks cheap. Its forward P/E of 5.3x is the lowest among the stocks we follow, and the average analyst target sits 41.1% above the current price. It’s still 13.3% below its 52-week high, though.
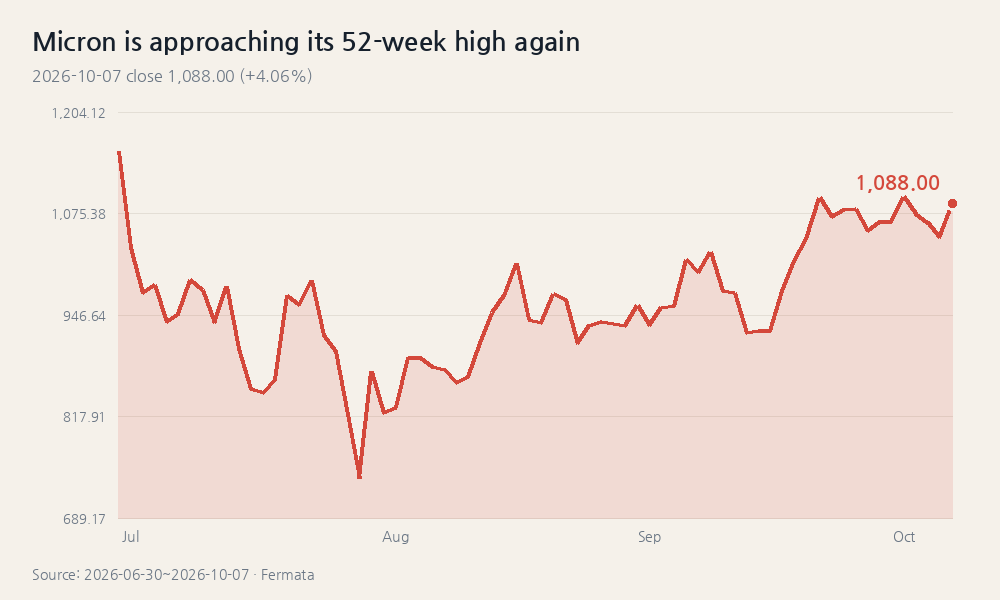

Photo: ThisisEngineering / Unsplash
Coinbase fell along with bitcoin
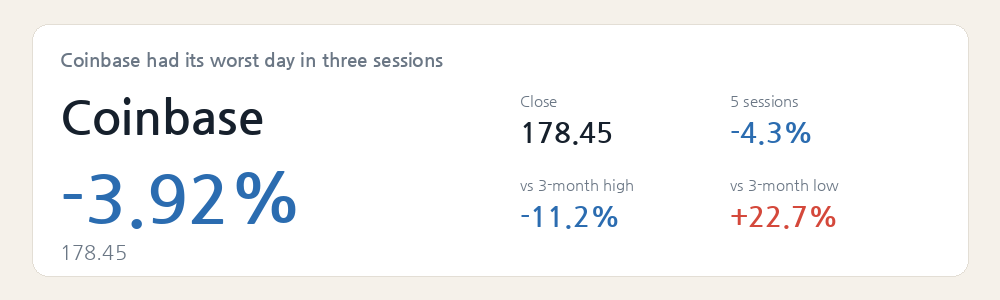
Coinbase fell 3.92% to $178.45 today. Bitcoin dropped nearly 2.7% to its lowest level since October 2 after renewed Iranian attacks in the Strait of Hormuz (Investing.com). Coinbase’s revenue leans heavily on trading fees, so its stock tends to move with bitcoin’s price.
Analysts were split. BTIG kept its Buy rating and $240 target, while Barclays kept its Underweight rating and $149 target.
Banks and industrials fell on rate worries
Higher rates are supposed to help banks that lend money, but not today. Citigroup, Wells Fargo, and Goldman Sachs all fell close to 2% — the worry was that rates rising this fast could cut into loan demand itself (CNBC).
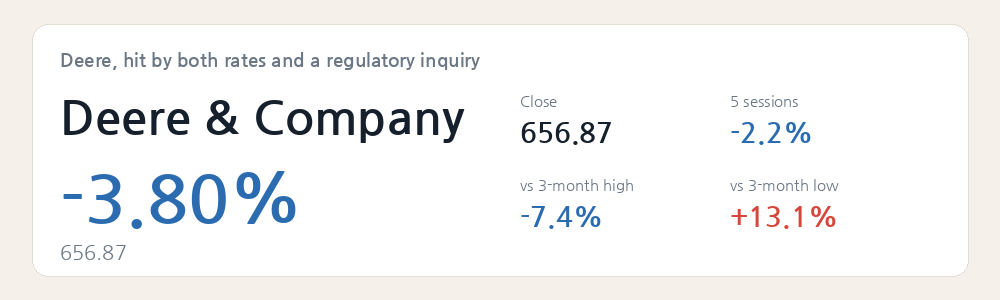
Industrials have been the worst-performing sector this week. Deere fell 3.80% to $656.87, hit not just by rates but by a joint FTC-USDA inquiry into whether farm-equipment makers are squeezing their market power (Investing.com). Caterpillar and other industrials fell on the same rate pressure.
Memory chips rose while logic chips fell
Within semiconductors, memory and logic chips went opposite ways. Micron (+4.06%) and SanDisk (+1.92%) rose on the memory-supply story, while AMD (-0.55%) and Marvell (-0.81%) fell and Broadcom (+0.19%) was roughly flat. The Philadelphia Semiconductor Index (SOXX) fell 1.12% — two memory names weren’t enough to lift the whole group.

SpaceX wobbled on a $40 billion debt plan
SpaceX fell 2.51% to $167.60 today. Bloomberg reported the company is seeking $40 billion in new debt — $10 billion in bank loans and $30 billion in investment-grade bonds — to buy Nvidia chips, with Apollo Global leading the financing.
What’s worrying investors is the pace of spending: SpaceX spent roughly $28.5 billion in capex in the first half of the year against only about $3.5 billion in operating cash flow — debt is filling the gap. A lock-up on 328.4 million shares also expires on October 9, which may have added to selling ahead of that date.
Another name among today’s most-traded stocks was Medtronic. The final exchange ratio for the spin-off of its diabetes unit, MiniMed, was set today, which drove heavier trading; the shares fell 1.81% to $85.51 (Investing.com).

Valuation check: Coinbase isn't cheap
Today’s drop doesn’t make Coinbase a bargain. Its forward P/E of 61.4x is the richest among the stocks we follow. Even so, the average analyst target sits 17.0% above the current price, and the stock is 55.6% below its 52-week high — an expensive stock that has also fallen the furthest.
Set against Micron and Intel, the gap is clear. Micron trades at 5.3x forward earnings with 41.1% of upside to target; Intel trades at 54.3x with just 4.4% of upside. Even within the same sector, how far a stock’s price has moved from its fundamentals varies name by name.

Today's rating changes centered on Moderna and Coinbase
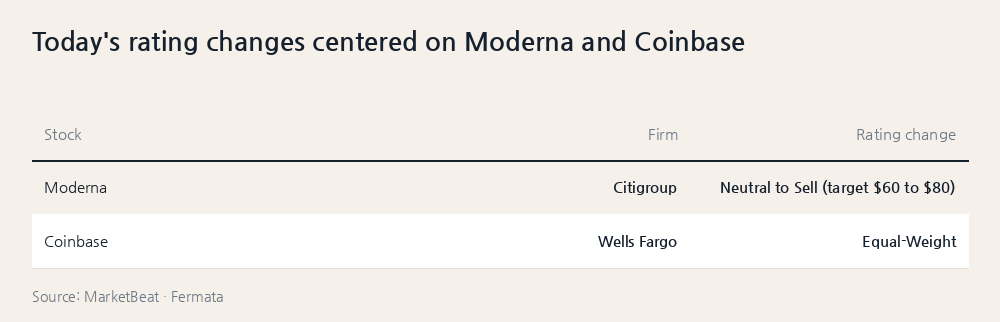
Only two rating changes came out over the past week, and both landed on stocks we covered today. Citi cut Moderna to Sell from Neutral on September 30 while raising its target to $80 from $60 — holding for existing holders, not a new buy at this level. Wells Fargo initiated Coinbase at Equal-Weight on October 2.
We’re skipping the 28 ratings that were left unchanged — only the changes carry a signal.
Oil rose on Iran tension, then gave it back
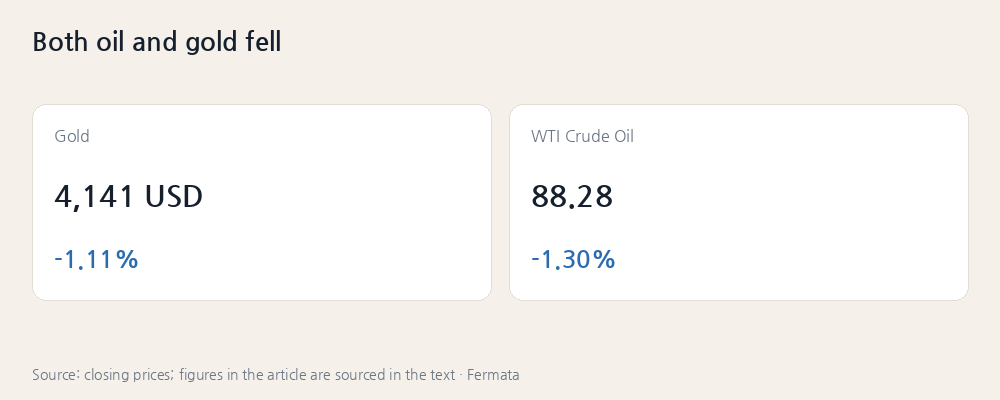
WTI crude fell 1.30% to $88.28 a barrel today. Prices jumped intraday on news of renewed Iranian attacks in the Strait of Hormuz, then gave up those gains after the IEA said it would release another 100 million barrels from reserves (Reuters, WSJ). Gold fell 1.11% to $4,140.70 an ounce — rising rates make non-yielding gold less attractive.
The link to tomorrow's Korean market is Micron
The first thing to watch when Korean markets open tomorrow is Micron. D.A. Davidson’s logic today — AI models using more memory, with demand outstripping supply in 2027-2028 — applies just as directly to SK Hynix and Samsung Electronics’ memory businesses. That’s the same reason Micron and SanDisk rose together today.
Treasury yields are also worth watching. Whether Korean equities can hold up while U.S. yields sit near 2002-era levels is something tomorrow’s session will test.
What to watch next session
First, whether Treasury yields retest today’s intraday high of 5.365%, or whether the calm after the $39 billion auction holds. Second, whether Micron’s rally spreads beyond SanDisk to the broader memory sector. Third, whether Moderna keeps swinging through its last sessions before the Nasdaq-100 inclusion on October 9.
Worth a closer look today
One index inclusion gave Moderna a three-day roller coaster
Moderna’s stock went $203.21 on Monday, $187.46 on Tuesday, and $196.48 today — three sessions all trading on the same story: its October 9 entry into the Nasdaq-100, taking the seat Warner Bros. Discovery is vacating.
Funds that track the Nasdaq-100 have to hold whatever’s in it, so buying often starts well before the effective date once inclusion is confirmed. That’s a mechanical explanation for Monday’s spike, Tuesday’s pullback, and today’s bounce.
That flow is separate from the company’s fundamentals, though. Citi cut Moderna to Sell from Neutral on September 30 while raising its target to $80 from $60 — a sign that index inclusion can move the price without changing the earnings or pipeline underneath it.
| Mon, Oct 5 | $203.21 |
| Tue, Oct 6 | $187.46 |
| Wed, Oct 7 (today) | $196.48 |
Coatue nearly 18x'd its Micron stake last quarter
With Micron and SpaceX both at the center of today’s market, a 13F filing shows hedge fund Coatue Management was already positioned in both as of the second quarter (June 30). It added 2,976,338 shares of Micron, a 1,794% increase, and opened a brand-new position of 18,561,780 shares in SpaceX.
The same filing shows Coatue opening a new Intel position of 12,084,027 shares, adding 3,904,033 shares of Amazon (+49%), and 342,979 shares of Broadcom (+6%) — buying into today’s memory and AI-infrastructure movers a quarter ahead of time.
13F filings are disclosed 45 days after the reporting date, though. These numbers are as of June 30, and we don’t know how much of these positions Coatue still holds — this is last quarter’s footprint, not today’s position.
| Micron | +2,976,338 shares (+1,794%) |
| SpaceX | +18,561,780 shares (new) |
| Intel | +12,084,027 shares (new) |
| Amazon | +3,904,033 shares (+49%) |
Fermata’s Take
We’re not reading today’s pullback in yields as an all-clear. The 10-year touched its highest level since 2002 (5.365%) intraday and only made it back to roughly yesterday’s level (5.28%) on strong auction demand — that’s not evidence the trend has turned. The split within semiconductors — memory (Micron +4.06%, SanDisk +1.92%) up, logic (AMD -0.55%, Marvell -0.81%) down — also says individual stories are driving prices, not the sector as a whole.
So we’re not adding to semiconductor exposure just because Micron rallied today. A 5.3x forward P/E and 41.1% of upside to target are attractive numbers, but there may be a reason the stock still sits 13.3% below its 52-week high. We want the supply-shortage thesis to show up in Micron’s next earnings before we’d add more.
Next session, we’ll check whether Treasury yields retest the mid-5.3% range, whether Micron’s rally spreads across the memory sector, and how Moderna trades through its final days before the Nasdaq-100 inclusion.
Check · 2026-10-08 — We check whether Treasury yields retest the mid-5.3% range, whether Micron's rally spreads to the broader memory sector (SanDisk and others), and how Moderna trades ahead of its October 9 Nasdaq-100 inclusion.
Sources
- CNBC Stocks making the biggest moves midday: Goldman Sachs, Webull, Worthington Steel, Micron & more
- Yahoo Finance Stock market today: Dow falls, S&P 500 and Nasdaq retreat from records amid bond market jitters
- Investing.com Bitcoin falls as Iran attacks, oil surge fuel rate fears; crypto stocks slip
- Investing.com Why is Deere & Company stock sliding today?
- Yahoo Finance SpaceX Slips 2% on a Reported $40 Billion Chip Financing Plan; Rocket Lab Eases, AST SpaceMobile Falls 3%
- Investing.com Moderna to join Nasdaq-100 index on Oct. 9, replacing Warner Bros.