Treasury Yields Hit a 24-Year High, Then Walked It Back
A Quiet Day for the Indexes, a Wild One for Yields
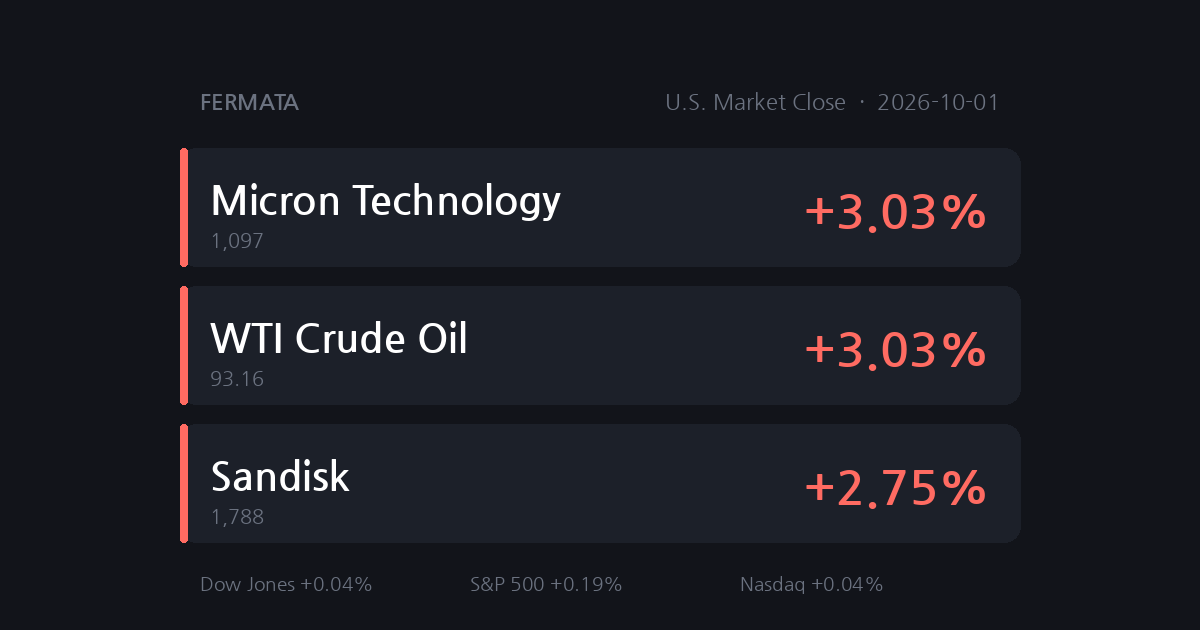
Wall Street’s first trading day of October looked calm on the surface. The Dow Jones Industrial Average added 0.04% to 50,926.56, the S&P 500 rose 0.19% to 7,666.45, and the Nasdaq Composite edged up 0.04% to 26,871.60. The small-cap Russell 2000 did better, up 0.35% to 2,806.62.
Underneath, Treasuries did the real moving. The 10-year yield touched an intraday high of 5.344%, its highest level since 2002, before closing lower than the prior session at 5.24% (CNBC). Individual stocks split sharply while yields swung — Micron jumped, while Broadcom and Alphabet both fell around 2%.

Checking Yesterday's Watch Items
Yesterday’s piece flagged three things to watch: how Micron’s stock would react to its earnings beat, whether that strength would carry into Korean chip stocks, and whether the 10-year yield would keep climbing past 5.29%.
Micron jumped 3.03% to $1,097.39, finally putting its earnings beat into the stock price. That strength did carry over to Korea — on the same calendar day in Korea, Samsung Electronics rose 2.79% and SK Hynix rose 3.21%, while the KOSPI gained 1.95% and the KOSDAQ jumped 4.48%.
The yield did clear 5.29% intraday, touching a fresh 2002-era high of 5.344%. But by the close it had actually fallen below the prior day’s level, to 5.24% — a new intraday record and a lower close, on the same day.

A 24-Year High, Then a Reversal
The 10-year Treasury yield hit 5.344% intraday, its highest level since 2002. The 30-year yield climbed near 5.7%, also nearing a 24-year high.
By the close, though, both had actually fallen versus the prior session — the 10-year ended down 1.06% at 5.24%, and the 30-year down 0.62% at 5.60%. A fresh record and a retreat landed on the same day.

Fed Officials Pushed Back on an October Hike
The pullback in yields traces partly to Fed officials. New York Fed President John Williams said there’s “no need for urgency” on an October rate hike, though he added one more hike “may be appropriate late this year” (Reuters).
Fed Governor Michael Barr struck a different note, saying “in my base case, further policy adjustments are likely to be needed” to bring inflation back to target. The split inside the Fed mirrors the split in how traders are now pricing October. More on that shift below.
Micron Jumped 3.03%
Micron Technology (MU) rose 3.03% to $1,097.39. Its fiscal fourth-quarter results — adjusted EPS of $33.42 and revenue of $5.423 billion, both above consensus — are finally showing up fully in the stock.
On valuation, Micron trades at 5.3 times next year’s expected earnings, among the cheapest names we follow. It’s still 39.8% below the average analyst price target and 12.6% below its 52-week high — a sign the earnings beat hasn’t been fully priced in yet.


Photo: ThisisEngineering / Unsplash
Broadcom Fell on Circular-Financing Worries
Broadcom, another chip name, moved the opposite way, falling 2.15% to $343.64. Reuters reported Broadcom is lending Anthropic up to $42 billion so the AI company can lease Broadcom’s chips — covering roughly a third of the $125.2 billion in compute capacity Anthropic has committed to over five years.
The loan is structured as convertible notes that could turn into Anthropic equity. What caught investors’ attention was the structure itself — Broadcom lends the money, and Anthropic uses it to buy Broadcom’s chips, a pattern CNBC described as raising “circular financing” concerns.
For readers new to the term: convertible notes start out as debt but can convert into equity under set conditions later. When one company lends money to another that then spends it buying the lender’s own products, that revenue can look stronger than the underlying demand really is. That concern weighed on Broadcom’s shares today.

Alphabet Fell Too, Without a Clear Trigger
Alphabet (GOOGL) fell 1.70% to $338.24, and its other share class (GOOG) fell 1.71% to $334.93. No specific negative headline broke on the company today.
The circular-financing concerns around Broadcom appear to have spread to other megacaps pouring money into AI infrastructure. Alphabet is itself one of the companies with the most aggressive data center and AI spending plans this year.

Oil Rose Again on Middle East Tensions
WTI crude rose 3.03% to $93.16 a barrel. Reuters reported the U.S. is sending another aircraft carrier to the Middle East, adding a third carrier strike group to a region that already had two.
Reports of continued attacks on tankers in the region added to the pressure. On a day when bond-market stress eased, oil emerged as the new variable.

Moderna Fell for a Second Day
Moderna, down more than 5% yesterday, fell another 1.89% to $188.94. Citigroup cut its rating on the stock to Sell from Neutral yesterday, and the shares have now declined for a second straight session since.
Today's Top Movers: Sandisk and AMD
Six stocks joined our list today on trading volume: Sandisk, AMD, Bloom Energy, Alphabet’s GOOG shares, SpaceX, and Broadcom. Sandisk led the gainers, up 2.75% to $1,787.69 — as another memory-chip maker, it moved in the same direction as Micron.
AMD rose a modest 0.65% and Bloom Energy 0.22%. SpaceX fell 1.85%, which appears tied to continued selling pressure after its post-IPO lockup expired on September 24 (Yahoo Finance).

What to watch next session
First, how yields and stocks react to Friday’s September jobs report (consensus: +84,000 jobs, 4.1% unemployment rate). Second, whether the AI-financing worries that hit Broadcom and Alphabet spread to other megacaps. Third, whether Micron’s rally continues.
Worth a Closer Look Today
Odds of an October Hike Fell Sharply in a Day
According to CME FedWatch data, the odds of a rate hike at the October FOMC meeting fell from 74.6% the day before to 49.4% today (Investing.com). New York Fed President John Williams saying there’s “no need for urgency,” plus a weaker-than-expected JOLTS job openings report, both weighed on the odds.
Not every Fed official agrees. Governor Michael Barr said further policy adjustments are likely needed in his base case, so a hawkish view still has a seat at the table. Markets are now treating Friday’s September jobs report as the next big test.
Broadcom Is Lending Anthropic Up to $42 Billion
Reuters reported, via Anthropic’s IPO prospectus, that Broadcom is lending the AI company up to $42 billion through convertible notes — covering roughly a third of the $125.2 billion in TPU compute capacity Anthropic has committed to over five years.
Broadcom has the option to bring in another financing partner, and the notes could convert into Anthropic equity. The relationship spans compute supply, equipment leasing, and now financing — Anthropic is set to become Broadcom’s largest customer in its core chip-design business next year.
The concern is the structure: Broadcom, Nvidia, and other companies funding Anthropic are all facing the same criticism — that the money they lend comes back to them as revenue when Anthropic spends it on their own chips, a pattern CNBC flagged as a circular-financing risk.
| Loan size | Up to $42 billion |
| Anthropic's 5-year TPU commitment | $125.2 billion |
| Structure | Convertible notes (can convert to equity) |
| Concern | Circular financing (Broadcom -> Anthropic -> Broadcom chip purchases) |
Fermata’s Take
We’re not summing today up as “a quiet day.” The 10-year Treasury yield set a fresh 2002-era high intraday and still closed below the prior session — that’s a market that’s lost some conviction about which way rates are headed next, and the Fed itself is split, with Williams and Barr pulling in different directions.
So with the October hike decision still genuinely open, we’re not adding to rate-sensitive positions ahead of the data — the jobs report, and eventually the FOMC meeting. We’re keeping names like Micron on watch, where the fundamentals are arguably still ahead of the price, and we’re not rushing into Broadcom or Alphabet on this dip until the financing structure behind the AI buildout is clearer in the numbers — specifically, how that revenue gets recognized.
Next session, we’ll check which way the jobs report pushes yields, and whether the fallout lands harder on Micron’s rally or on Broadcom’s financing story.
Check · 2026-10-02 — How yields and stocks react to the September jobs report (consensus +84,000 jobs, 4.1% unemployment), whether the AI-financing and circular-financing concerns that hit Broadcom and Alphabet continue, and whether Micron's rally holds up.
Sources
- CNBC Stock market today: Live updates
- CNBC Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Investing.com Fed rate hike bets for Oct fall sharply on soft data, dovish comments
- CNBC Brent oil jumps more than 4% as U.S. reportedly sends third aircraft carrier to Middle East
- CNBC The September jobs report will be released Friday. Here's what to expect
- Yahoo Finance SpaceX Extends Decline as Valuation Concerns Weigh on Post-IPO Momentum