We're Not Chasing Today's Sandisk Rally
Today's mood
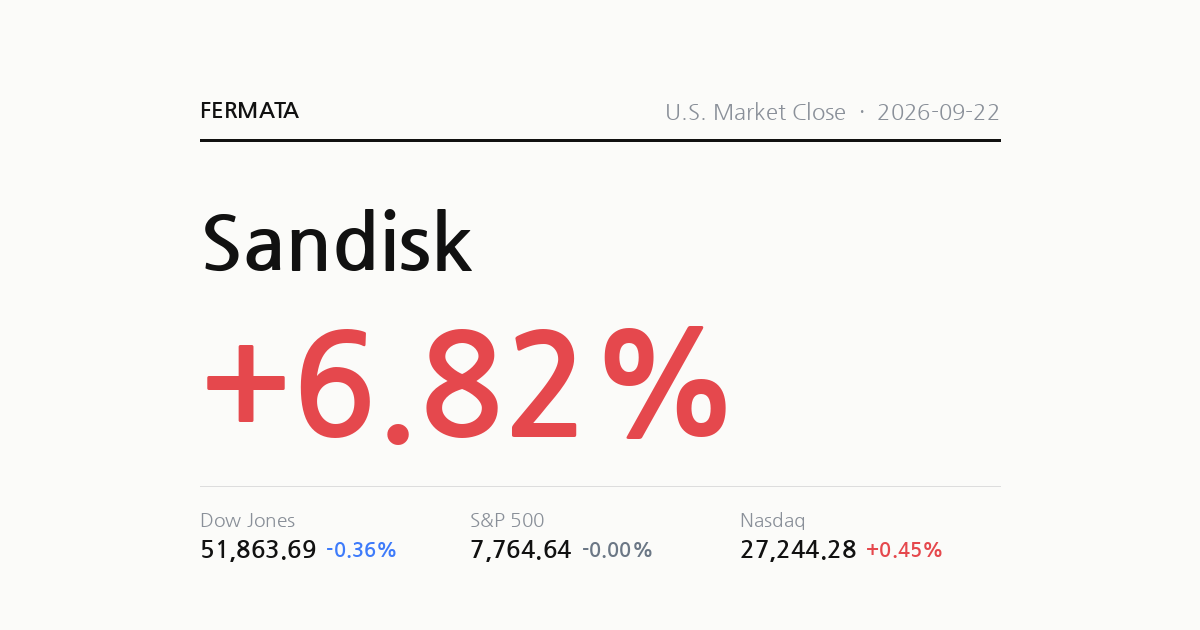
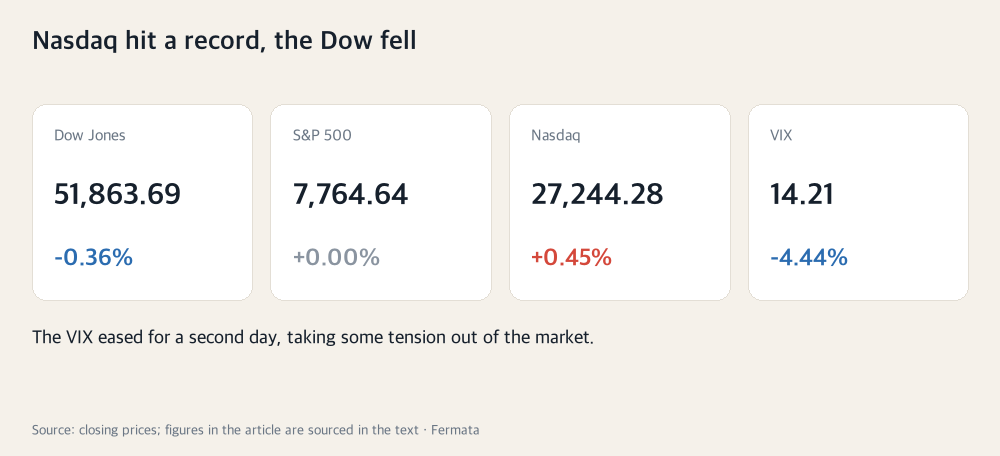
By the headline numbers it was another quiet session. The Nasdaq Composite rose 0.45% to a fresh record of 27,244.28, its second straight all-time high. The S&P 500 was flat at 7,764.64, and the Dow slipped 0.36% to 51,863.69. The VIX fell another 4.44% to 14.21.
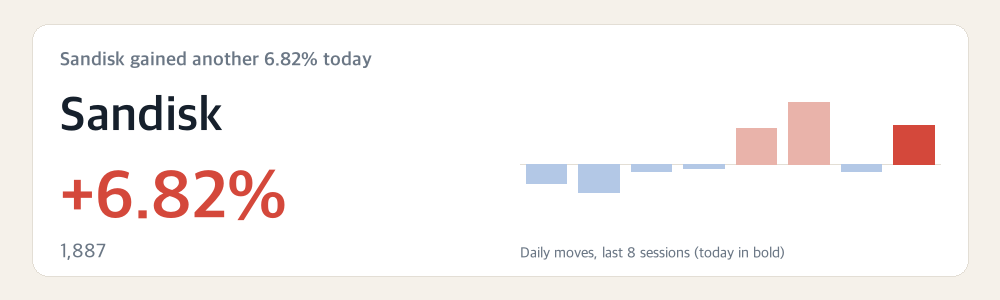
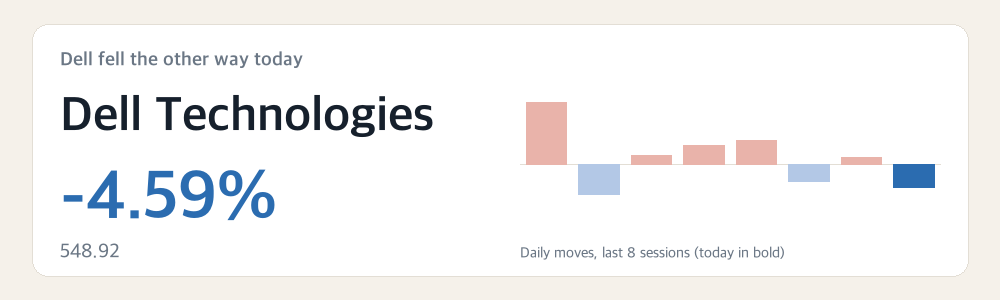
Underneath, the split was as sharp as yesterday’s. Memory-chip maker Sandisk jumped another 6.82% and Micron gained 5.00%, extending its run to fresh highs. Banks, insurers and travel names moved the other way, and Dell fell 4.59% on its own. The index was calm; where the money went was not.
Yesterday's checkpoints, today's answer
Yesterday we flagged three things: whether Meta’s 11.34% jump would hold, whether Intel and AMD would stay among the day’s most actively traded names, and whether oil and yields would stabilize.
Meta gave back just 0.63% today, closing at $736.59 – most of yesterday’s gain held. Intel rose another 1.71% and AMD gained 1.34%, both staying among today’s most actively traded names. That part checks out.
Oil did not stabilize – WTI fell another 6.35%, a fourth straight down day. The 10-year yield rose only 0.10 points to 4.97%, not far from where it sat yesterday, so call that one a partial hit. Warner Bros. Discovery and Strategy dropped out of today’s most-active list, so we couldn’t verify them directly from our data – though Benzinga reported Warner Bros. Discovery trading near its 52-week high on Paramount Skydance merger-talk news.
Chips lifted the Nasdaq; banks dragged the Dow
CNBC and Yahoo Finance tied today’s record Nasdaq close to renewed strength in semiconductor and AI-infrastructure names. Meta’s AI agent Muse, launched September 8, has topped Apple’s free-app charts, and its popularity is refocusing attention on the memory and GPU demand needed to run it.
The Dow fell the other way, dragged down by banks and insurers. If an AI assistant like Muse can handle bookings, subscription cancellations and currency exchange on a user’s behalf, the financial-services habits consumers keep out of inertia could get cleaned up automatically – and that risk showed up in prices for the first time today.
Banks, insurers and travel stocks sold off together
Bloomberg reported the S&P 500 financials index shed nearly 2% to close at its lowest level since July. JPMorgan and Wells Fargo each fell more than 3%, Morgan Stanley dropped 2.9%, Allstate fell 5.5%, and Charles Schwab lost more than 6%.
Bloomberg framed the selloff as a repricing of business models that depend on ‘consumer inertia.’ If agents like Muse start canceling neglected subscriptions, renegotiating phone plans, and moving cash into higher-yielding accounts, the revenue base of banks, insurers and travel bookings that customers keep out of habit could be at risk.

Sandisk was today's biggest mover
Sandisk closed up 6.82% at $1,887.04, the largest move among the names we track today. Invezz reported Rosenblatt Securities initiated coverage with a Buy rating and a $2,400 price target, arguing NAND memory is shifting from a commodity storage medium into a system-critical part of AI infrastructure.
Index flows added to the move. 24/7 Wall St. reported Sandisk joined the S&P 100 on September 21, and index-tracking funds have been buying ahead of that change all week. Both catalysts are one-day news, though – no earnings came out today.
Micron keeps climbing a week before earnings
Micron rose 5.00% to $1,096.16. With fiscal Q4 results due September 30, tight memory supply and strong demand expectations keep pushing the stock higher. On forward earnings, Micron trades at 6.9x – 38.2% below its price target and 12.7% below its 52-week high.
Beginner’s note: forward P/E divides today’s share price by the profit analysts expect over the next year. A lower number means the stock is cheap relative to expected earnings. Forty-six analysts cover Micron, and even after today’s gain the stock still trades below its price target.


Photo: ThisisEngineering / Unsplash
Dell went the other way, down 4.59%
Dell Technologies fell 4.59% to $548.92. GuruFocus pointed to the stock still trading above its valuation estimate and a full year of insider selling with no insider buying as the backdrop for today’s decline.
Dell joined the S&P 100 alongside Sandisk last week. That the two stocks that shared the same index-inclusion catalyst went opposite directions a week later shows that inclusion flows alone don’t explain where a stock goes next.
Moderna gained again on cancer-vaccine hopes
Moderna rose 5.56% to $182.56, extending a rally that began last month when its melanoma cancer vaccine, developed with Merck, met its endpoints in a Phase 3 trial. A recent FDA approval of its updated 2026-2027 shots is adding COVID-related revenue expectations on top of that.
The next test comes October 24, when survival data is due at the European Society for Medical Oncology conference – a result that could confirm this run or reverse it, which keeps the volatility high.

Oil fell for a fourth straight day
WTI crude dropped 6.35% to $89.70 a barrel, extending its losing streak to four sessions. Reuters and CNBC pointed to easing US-Iran diplomatic tension and continued, largely undisrupted oil and LNG shipping through the Strait of Hormuz.
Gold moved the other way, up 0.40% to $4,401.40 an ounce – a sign that safe-haven demand held even as supply fears around oil eased.

Treasury yields stalled near 5%
The 10-year Treasury yield rose 0.10 points to 4.97%, and the 30-year climbed 0.13 points to 5.30%. Yields have hovered near 5% all week since the Fed’s rate hike last week, its first in three years.
St. Louis Fed President Alberto Musalem said further rate increases may be needed to bring inflation back to target – one reason the market is treating last week’s hike as a first step rather than a one-off.

Walmart and Deere quietly gained too
Walmart rose 2.49% to $110.12 and farm-equipment maker Deere gained 2.69% to $703.12. With attention split between chip stocks and the bank selloff, a quiet gain in consumer and industrial bellwethers suggests the broader market isn’t as fragile as the day’s extremes might suggest.
The Philadelphia Semiconductor Index (SOXX) rose 2.40%, showing the single-stock rally is spreading across the sector.
What carries into Korea's next session
Sandisk and Micron’s second straight day of big gains is a reference point for Samsung Electronics and SK Hynix. But TipRanks reported that in premarket trading today, Micron and SK Hynix’s US ADR actually dipped slightly while only Sandisk rose – a sign that caution ahead of Wednesday’s Trump-Xi summit still lingers over semiconductor supply-chain names, so the direction at Korea’s open is worth watching closely.
Today’s bank and insurer weakness is also worth watching for Korean financials, though the ‘consumer inertia’ story is still specific to the US AI-agent market – it’s too early to apply the same logic directly to Korean banks.
What to watch next session
First, whether the September 24 Trump-Xi summit touches on semiconductor supply chains and whether that affects Micron and Sandisk’s gains. Second, whether today’s bank and insurer decline is a one-day reaction or a multi-day repricing. Third, whether WTI crude finds support near $90 after four straight down days.
What we learned today
Why Micron still looks like the cheapest name
Lined up against today’s other chip and memory gainers, Micron is still the cheapest on forward earnings: 6.9x, with 38.2% upside to its price target and still 12.7% below its 52-week high. Forty-six analysts cover the stock.
Beginner’s note: forward P/E divides today’s share price by the profit analysts expect over the next year. A lower number means the stock is cheap relative to expected earnings; a higher one means the market has already priced in a lot of growth.
Nvidia trades at 14.6x forward earnings – more than double Micron’s multiple – but still has 43.2% upside to its own price target, a reminder that a pricier-looking stock doesn’t always have less room to run.
| Micron: fwd P/E · upside to target · vs. 52-wk high | 6.9x · +38.2% · -12.7% |
| Nvidia: fwd P/E · upside to target · vs. 52-wk high | 14.6x · +43.2% · -3.2% |
Funds were building Micron and SpaceX stakes three months ago
13F filings as of June 30 show hedge fund Coatue Management increased its Micron stake by 2,976,338 shares (+1,794%) and built a new 18,561,780-share position in SpaceX. Both names moved sharply today – Coatue had been adding to them three months before the fact.
13F filings only become public 45 days after their reference date – they’re a snapshot of last quarter, not today’s positioning. The same filing shows Coatue added 49% to its Amazon stake, while Berkshire Hathaway cut its Bank of America stake by 6% – in the same direction as today’s bank weakness.
| Coatue Management · Micron | +2,976,338 shares (+1,794%) |
| Coatue Management · SpaceX | +18,561,780 shares (new) |
| Berkshire Hathaway · Bank of America | -30,230,150 shares (-6%) |
Fermata’s Take
We read Sandisk’s 6.82% gain as a one-day combination of Rosenblatt’s new Buy rating and S&P 100 index-inclusion flows, not a structural re-rating. The evidence is Dell – a stock that shared the same index-inclusion catalyst fell 4.59% a week later. Two stocks catching the same tailwind moving in opposite directions tells us that catalyst alone doesn’t explain where a stock goes.
Next session we’ll check whether the September 24 Trump-Xi summit touches on semiconductor supply chains, and whether today’s bank and insurer decline is a one-day reaction or something that continues.
So we’re not chasing today’s Sandisk rally – one new coverage initiation and index-inclusion flows aren’t enough to chase a stock that’s already run this far. But we’re keeping a name like Micron, with 38.2% upside to its price target and still 12.7% below its 52-week high, on our list of valuation candidates to scale into, independent of today’s single-name news.
Check · 2026-09-23 — Whether Micron and Sandisk's gains hold the day before the September 24 Trump-Xi summit, whether today's bank and insurer decline (JPMorgan, Wells Fargo, Morgan Stanley and others) continues into the next session, and whether WTI crude finds support near $90.
Sources
- CNBC Stock market today: Dow slips, Nasdaq posts fresh record with AI trade, Trump diplomacy in focus
- Bloomberg Meta's Muse AI Agent Drives Selloff in Banks, Insurers, Travel Stocks
- Investing.com SanDisk stock could climb 35% more, Rosenblatt says with a $2,400 target
- Yahoo Finance Micron, SanDisk Lead Memory Chip Stocks Rally on Strong AI Demand
- Bloomberg Meta's Muse AI Agent Fuels Chip Stock Rally
- CNBC Treasury yields are little changed as traders await Fed comments
- Investing.com Why is SanDisk stock surging today?
- Yahoo Finance Why Are Micron and SKHY Stocks Falling While SanDisk Is Rising in Premarket Today, Sept. 22? (TipRanks)