Chips Roar Back as the VIX Collapses, But Bank Stocks Miss the Party
Today's mood
A day after the Fed raised interest rates for the first time since 2023, markets did an about-face. Yesterday all three major indexes were higher before Fed Chair Kevin Warsh’s hawkish comments sent them into the red by the close; today undid most of that damage.
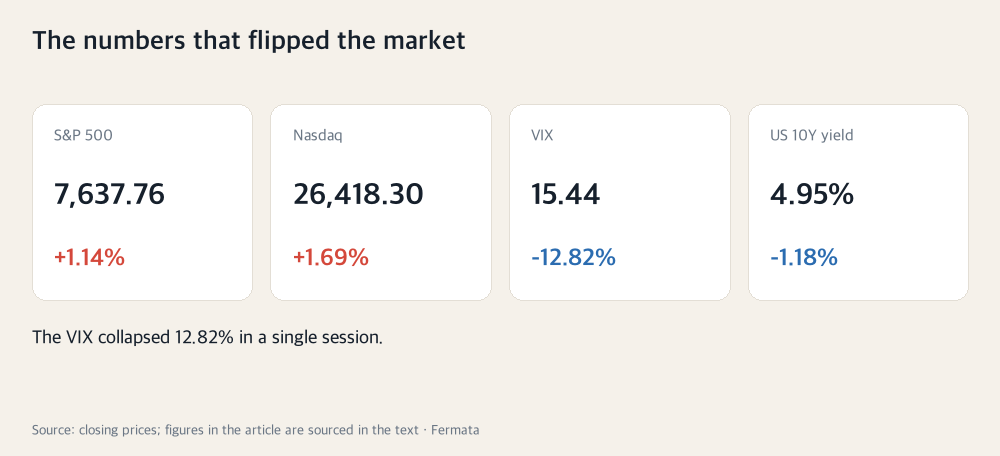
The S&P 500 rose 1.14% to 7,637.76, the Nasdaq Composite gained 1.69% to 26,418.30, and the Dow added 0.61% to 51,778.04. The VIX, Wall Street’s fear gauge, plunged 12.82% to 15.44, unwinding much of the anxiety that built up yesterday.
Checking yesterday's watch items
In yesterday’s close we said we’d watch two things: whether the bank selloff was a one-day move, and whether the 10-year Treasury yield would clear Tuesday’s intraday high of 5.04%.
The yield question is answered. The 10-year fell to 4.95% today, below yesterday’s 5.01% close, and never approached 5.04%. Yields snapped an eight-day rising streak (Yahoo Finance).
The bank question is harder to close out. Investing.com reported that Bank of America, Wells Fargo, Citigroup, Goldman Sachs and JPMorgan all fell in tandem right after yesterday’s Fed decision, and reporting today suggested financials again lagged the broader rebound, trailing tech and materials. It is too early to call the selloff a one-day event.

Bonds and oil did the calming
Today’s rally was built outside the stock market, in bonds and commodities. As yields and oil both eased, the inflation vigilance Chair Warsh voiced yesterday faded within a day.
WTI crude fell 1.31% to $101.09 a barrel as reports that Saudi Arabia’s East-West pipeline disruption would soon be resolved weighed on Brent as well (Yahoo Finance). Gold barely moved, down 0.09% to $4,383.60 an ounce.
Falling oil eased inflation math for bond investors, pulling Treasury yields lower — and that, in turn, gave equity investors room to buy risk assets again.

Chips rallied across the board
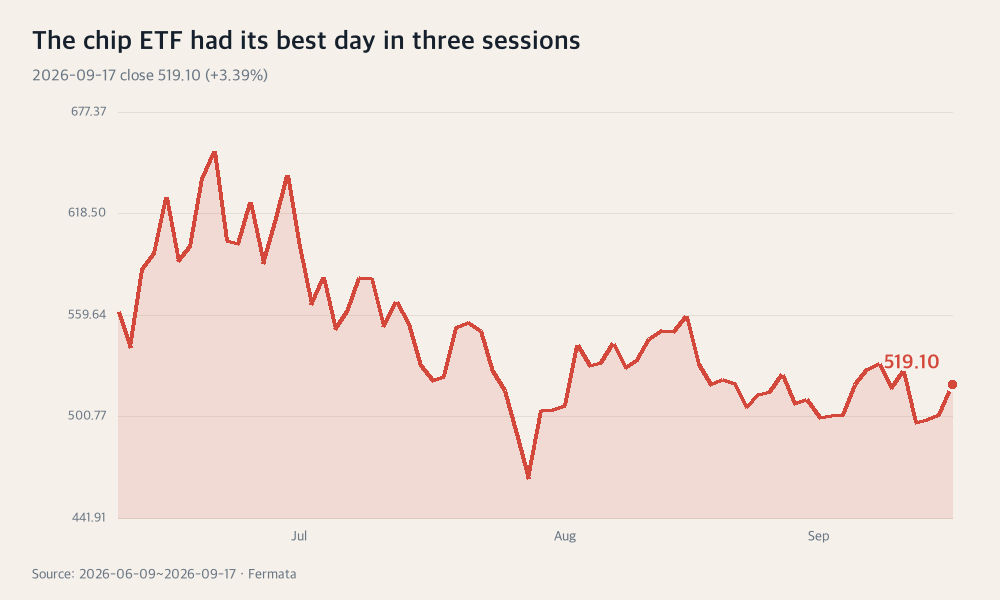
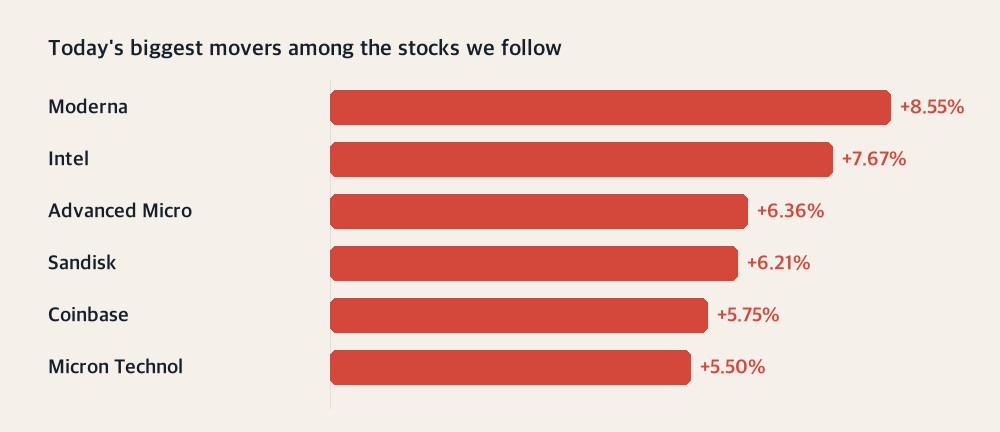
Semiconductors sat at the center of the rebound. The Philadelphia Semiconductor Index jumped more than 3%, and the chip ETF we track (SOXX) rose 3.39%. Micron gained 5.50%, AMD rose 6.36%, and Intel jumped 7.67%.
Two threads fed the move. Intel CEO Lip-Bu Tan told an industry event that the memory-chip bottleneck would worsen into 2027, with capacity very constrained and prices already up a lot (Yahoo Finance), and a report that SK Hynix and Intel are discussing US memory production resurfaced.
Micron’s forward price-to-earnings ratio is 6.3x, the lowest among the stocks we follow, with 54.8% of implied upside to the average analyst target and a 22.1% gap to its 52-week high.
The Intel-SK Hynix Ohio story got more specific
Talk of SK Hynix-Intel cooperation was already in the air yesterday, but today it got a sharper outline. Reuters, citing people familiar with the matter, reported the two are discussing SK Hynix leasing part of Intel’s planned Ohio campus, or forming a joint venture with major cloud customers (Investing.com).
Intel pledged up to $100 billion for the Ohio site back in 2022, though the two planned plants are not expected to finish until 2030 and 2031. SK Hynix is a leading supplier of HBM, a key component in AI chips.
Both companies were careful to hedge. SK Hynix said no decisions have been made on either scenario, and Intel did not respond to requests for comment (TechCrunch). Today’s 7.67% move in Intel shares is riding on an unconfirmed report, not a signed deal.
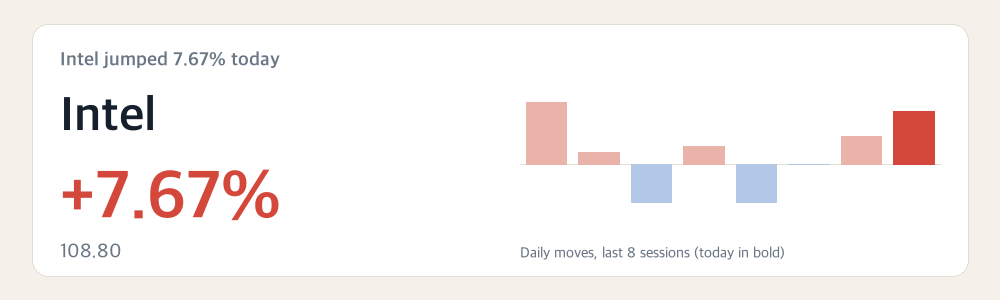
Photo: DrHughManning / Wikimedia Commons (BY-SA 4.0)
Mega-caps rose broadly too
Chips weren’t the whole story. Nvidia added 2.54%, Amazon rose 2.13%, Microsoft gained 1.52%, and Alphabet rose 1.30% as large-cap tech advanced across the board. Tesla gained 2.27%, and farm-equipment maker Deere rose 2.41%, trading near a record high.
Nvidia’s forward P/E is 14.0x, with 49.8% of implied upside to target — but only 7.3% below its 52-week high, making it one of the stocks we track that’s already closest to its peak.
Not everything rose: Walmart slipped 0.66%.
CoreWeave was the exception
On a day when chips and AI names rallied together, data-center operator CoreWeave went the other way, falling 4.16% to $79.88.
CoreWeave announced a convertible senior notes offering of up to $3 billion (with room to grow to $3.5 billion) alongside an at-the-market program for up to 35 million shares, to fund AI compute buildout (The Motley Fool).
In plain terms: a convertible note is a bond that can later turn into stock under set conditions. It lets a company borrow more cheaply, but if it converts, existing shareholders’ stakes get diluted. CoreWeave’s total liabilities of $72 billion are more than fourteen times its $5 billion in equity, and guided Q3 interest expense of $860-940 million added to concerns that this raise adds financial strain.
That overshadowed 112% year-over-year revenue growth. Rival Nebius, by contrast, rose 4.12% — investors noted it is funding its own expansion from existing cash (The Motley Fool).

Banks missed the rebound
Today’s gains were not evenly spread. Tech led the index higher while financials and energy lagged, according to market reporting.
Bank of America, Wells Fargo, Citigroup, Goldman Sachs and JPMorgan all fell right after yesterday’s Fed decision (Investing.com), and today the sector again failed to keep pace with the broader rebound. Higher rates were cited as the reason: they can cool loan demand and raise the risk of credit losses if growth slows.
We don’t track major bank stocks directly among the names we follow. But a session led by chips rather than banks fits the call we made in yesterday’s close — that the risk was concentrated in banks, not semiconductors or AI infrastructure broadly.
Moderna and Coinbase also jumped
Among individual names, Moderna led with an 8.55% gain to $158.07. Analysts linked it to a month-long rally in the melanoma mRNA vaccine trade, though we could not confirm a fresh, dated catalyst specific to today.
Coinbase, which had fallen for two straight sessions, rebounded 5.75% to $173.97. Compass Point upgraded the stock from Sell to Neutral last week, and today’s broad risk-on mood compounded the bounce.
Sandisk rose 6.21% and SpaceX gained 2.60% as well.

What carries over to Korea's open
Today’s US headlines matter for tomorrow’s Korean session too. The Reuters-reported Intel-SK Hynix Ohio talks lifted SK Hynix’s US-listed ADR, and could ripple into Korean semiconductor and memory names on the same story.
SK Hynix also flagged that any such arrangement could qualify as one of Korea’s ‘national core technologies,’ requiring government review before it goes forward (TechCrunch) — a reminder that several steps remain before this becomes a real deal.
A 3%-plus rally in the US chip index is a favorable backdrop for Korea’s large semiconductor names. But just as US bank stocks missed today’s rebound, sector performance in Korea could be uneven too.
What we're watching next session
First, whether the Intel-SK Hynix Ohio talks turn into something more concrete. Both companies are still saying nothing has been decided.
Second, whether banks again lag the broader market tomorrow — that will tell us whether today’s underperformance was one day of hawkish-Fed hangover or something stickier.
Third, whether CoreWeave’s convertible notes and share sale keep weighing on the stock after today’s 4.16% drop, or whether it stabilizes.
What we learned today
Berkshire added Alphabet and trimmed Bank of America as of June 30
13F filings are released 45 days after the reporting date, so this reflects positioning as of June 30, not today. Still, the filing shows Warren Buffett’s Berkshire Hathaway added 24,541,369 Alphabet Class A shares (+45%) and 23,603,218 Class C shares (+658%) as of that date. It also added 17,510,544 Delta Air Lines shares (+44%).
On the other side, Berkshire cut Bank of America by 30,230,150 shares (-6%) and Kroger by 11,000,000 shares (-22%). That direction — adding tech, trimming a bank — lines up with today’s session, where Alphabet rose 1.30% and financials broadly lagged the rebound.
Given the reporting lag, we can’t say whether Berkshire holds the same view today. But the tilt toward big tech over banks is worth weighing against today’s sector leadership.
| Berkshire, Alphabet Class A change | +24,541,369 sh (+45%) |
| Berkshire, Alphabet Class C change | +23,603,218 sh (+658%) |
| Berkshire, Bank of America change | -30,230,150 sh (-6%) |
| 13F reporting date | 2026-06-30 |
Micron has 54.8% of upside to its average target

Comparing valuations among today’s biggest movers, Micron looks the cheapest among the stocks we track. Its forward P/E is 6.3x, with 54.8% of upside to the average analyst target and a 22.1% gap to its 52-week high, across coverage from 45 analysts.
Intel’s forward P/E of 52.8x looks over eight times richer, but it still has 7.0% of implied upside to target. It remains 23.6% below its 52-week high even after this week’s rally.
Coinbase carries the highest forward P/E of the three at 61.4x. It has 16.1% of upside to target but sits 56.7% below its 52-week high — a number that confirms, on its own, how volatile the stock has been.
| Micron: fwd P/E · upside to target · vs. 52wk high | 6.3x · +54.8% · -22.1% |
| Intel: fwd P/E · upside to target · vs. 52wk high | 52.8x · +7.0% · -23.6% |
| Coinbase: fwd P/E · upside to target · vs. 52wk high | 61.4x · +16.1% · -56.7% |
Fermata’s Take
We read today’s rally as a chip-led rebound, not a bank-led one. The chip ETF (SOXX) rose 3.39% and drove the index higher, while reporting suggests financials never shook off yesterday’s post-Fed weakness.
That said, much of today’s move in Intel, Micron and SK Hynix-linked names is riding on an Ohio joint-venture report that both companies say remains undecided. A headline, not a signed deal, drove a big share of today’s gain — too early to treat this as an earnings-driven re-rating.
Next session we’ll check whether that Ohio talk turns into a concrete announcement, and whether banks keep lagging the market.
So we’re not chasing today’s chip rally on the strength of one report alone — not until a deal is actually signed. But we’re keeping a name like Micron, with 54.8% upside to target and still 22.1% below its 52-week high, on our list of valuation candidates to scale into, independent of today’s headline.
Check · 2026-09-18 — Whether the Intel-SK Hynix Ohio talks produce a concrete announcement, whether banks again lag the S&P 500 tomorrow, and whether CoreWeave stabilizes after its convertible-note and share-sale announcement.
Sources
- Yahoo Finance Stock Market Today (Sept. 17, 2026): Dow surges after Fed rate hike decision
- Yahoo Finance Stock market today: Dow, S&P 500, Nasdaq rebound as bond yields slip, oil eases
- Investing.com Big U.S. bank stocks fall after Fed raises interest rates
- Investing.com Premarket movers: Intel jumps on SK Hynix memory-chip talks, J.B. Hunt slides
- TechCrunch SK Hynix reportedly in talks with Intel to build memory chips in US
- The Motley Fool Stock Market Today, Sept. 17: CoreWeave Falls on Convertible Debt and Share Sale Announcement